Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
Natural justice and pre-CIRP labour awards protect termination compensation, permitting withdrawal of court deposits despite later insolvency resoluti...
Arbitration of SEZ sub-lease monetary claims preserves rent, maintenance, termination, improvements and damages disputes while unused premises are vac...
Scientific research approval grants a research association tax recognition, subject to annual donor reporting, certification, and regulatory complianc...
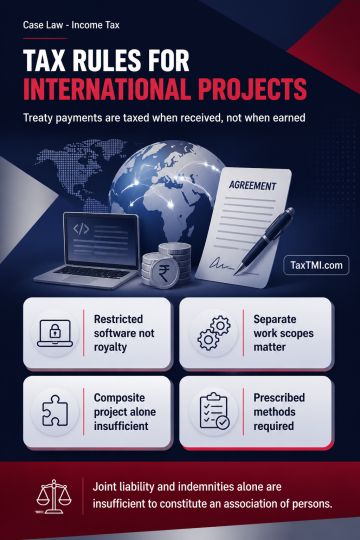
Royalty and fees for technical services under the India-Germany DTAA are taxable on receipt rather than accrual basis. Consideration for restricted, non-exclusive standard software licences that do not transfer copyright rights is not royalty under the Act or treaty. Separate scopes of work, invoicing, consideration and no profit-and-loss sharing prevent consortium members from constituting an association of persons; joint and several liability and indemnities alone are insufficient. Offshore equipment-supply income is not taxable in India merely because it forms part of a composite project. Transfer-pricing adjustments require a prescribed method and cannot rest on an ad hoc mark-up where transaction differences are reconciled and benchmarking is undisputed.
Royalty and fees for technical services under the India-Germany DTAA are taxable on receipt rather than accrual basis. Consideration for restricted, non-exclusive standard software licences that do not transfer copyright rights is not royalty under the Act or treaty. Separate scopes of work, invoicing, consideration and no profit-and-loss sharing prevent consortium members from constituting an association of persons; joint and several liability and indemnities alone are insufficient. Offshore equipment-supply income is not taxable in India merely because it forms part of a composite project. Transfer-pricing adjustments require a prescribed method and cannot rest on an ad hoc mark-up where transaction differences are reconciled and benchmarking is undisputed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888