Separate speaking orders on reopening objections are mandatory; deciding them within reassessment invalidates jurisdiction and precludes revival of st...
Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Page of 4888
Press 'Enter' after typing page number.
41 to 60 of 97750 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
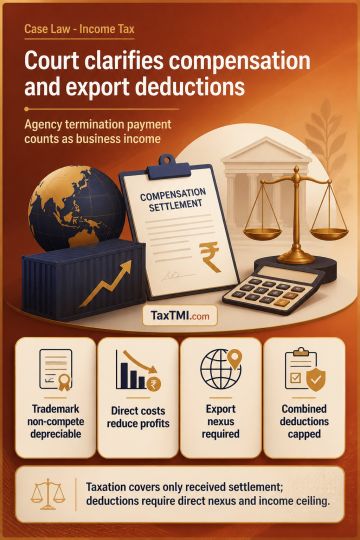
Termination compensation under a distribution arrangement that is substantively an agency relationship is treated as business income rather than a capital receipt, and taxation is confined to the settlement actually received. A non-compete covenant integral to acquiring and protecting a trademark qualifies as a depreciable intangible asset. For section 80-IB, only costs directly connected with an eligible undertaking should reduce its profit; allocation of finance, research, travel, head-office and export-promotion costs depends on factual nexus. Section 80HHC excludes receipts lacking a direct export nexus, while concurrent 80-IB and 80HHC deductions remain subject to the gross-total-income ceiling. A purely legal additional ground based on the existing record may be considered.
Termination compensation under a distribution arrangement that is substantively an agency relationship is treated as business income rather than a capital receipt, and taxation is confined to the settlement actually received. A non-compete covenant integral to acquiring and protecting a trademark qualifies as a depreciable intangible asset. For section 80-IB, only costs directly connected with an eligible undertaking should reduce its profit; allocation of finance, research, travel, head-office and export-promotion costs depends on factual nexus. Section 80HHC excludes receipts lacking a direct export nexus, while concurrent 80-IB and 80HHC deductions remain subject to the gross-total-income ceiling. A purely legal additional ground based on the existing record may be considered.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888