Appellate jurisdiction over baggage imports is excluded, requiring confiscation challenges involving passenger-carried gold to proceed by statutory re...
Article 227 review permits intervention in arbitration only for manifest, patent inherent jurisdictional defects, not representational authority dispu...
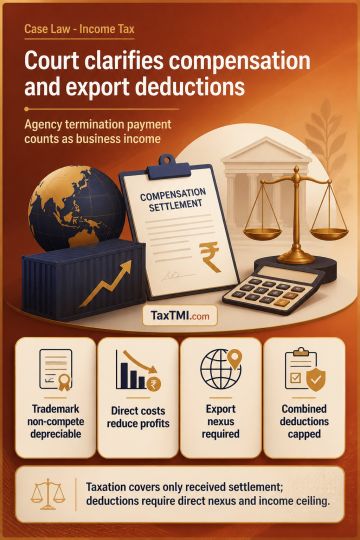
Termination compensation under a distribution arrangement that is substantively an agency relationship is treated as business income rather than a capital receipt, and taxation is confined to the settlement actually received. A non-compete covenant integral to acquiring and protecting a trademark qualifies as a depreciable intangible asset. For section 80-IB, only costs directly connected with an eligible undertaking should reduce its profit; allocation of finance, research, travel, head-office and export-promotion costs depends on factual nexus. Section 80HHC excludes receipts lacking a direct export nexus, while concurrent 80-IB and 80HHC deductions remain subject to the gross-total-income ceiling. A purely legal additional ground based on the existing record may be considered.
Termination compensation under a distribution arrangement that is substantively an agency relationship is treated as business income rather than a capital receipt, and taxation is confined to the settlement actually received. A non-compete covenant integral to acquiring and protecting a trademark qualifies as a depreciable intangible asset. For section 80-IB, only costs directly connected with an eligible undertaking should reduce its profit; allocation of finance, research, travel, head-office and export-promotion costs depends on factual nexus. Section 80HHC excludes receipts lacking a direct export nexus, while concurrent 80-IB and 80HHC deductions remain subject to the gross-total-income ceiling. A purely legal additional ground based on the existing record may be considered.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI