Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
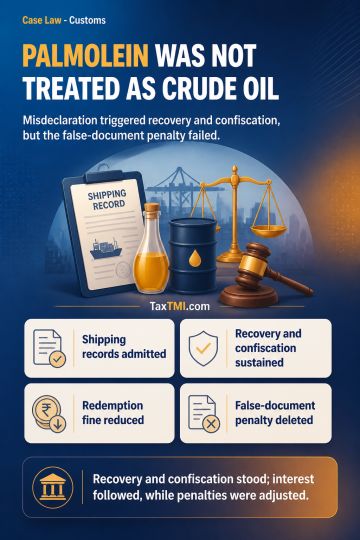
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
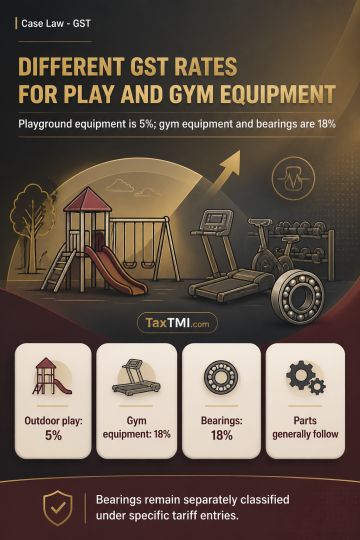
Outdoor playground equipment, including qualifying spare parts, is classified under tariff item 95069990 as sports goods and taxable at 5%. Outdoor gym equipment and its qualifying spare parts are classified under tariff item 95069190 as equipment for general physical exercise and taxable at 18%. Parts solely or principally used with Chapter 95 articles generally follow the equipment classification. Ball and roller bearings remain separately classifiable under Heading 8482 because that specific tariff entry prevails over the general parts classification; their applicable tariff entry depends on their specifications, and they are taxable at 18%.
Outdoor playground equipment, including qualifying spare parts, is classified under tariff item 95069990 as sports goods and taxable at 5%. Outdoor gym equipment and its qualifying spare parts are classified under tariff item 95069190 as equipment for general physical exercise and taxable at 18%. Parts solely or principally used with Chapter 95 articles generally follow the equipment classification. Ball and roller bearings remain separately classifiable under Heading 8482 because that specific tariff entry prevails over the general parts classification; their applicable tariff entry depends on their specifications, and they are taxable at 18%.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931