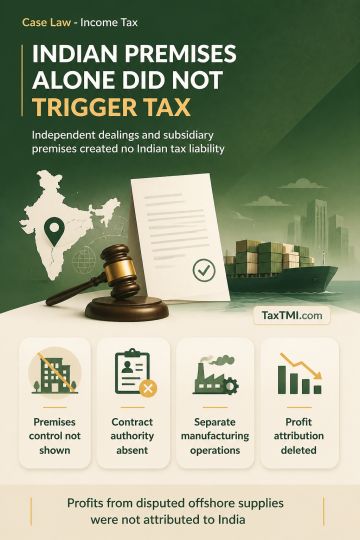
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
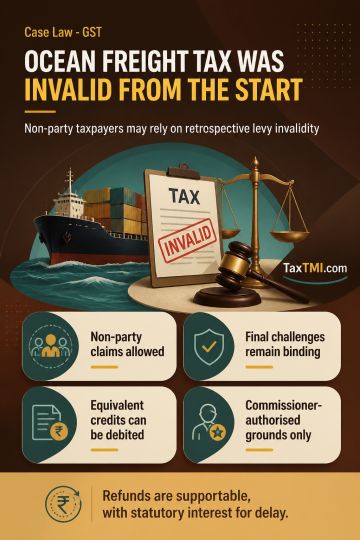
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income com...
Modified returns after business reorganisations cannot trigger fresh scrutiny once the original assessment was complete, invalidating related transfer...
Page of 4929
Press 'Enter' after typing page number.
781 to 800 of 98580 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Tax payable is material to prosecution for failure to furnish a return under Section 276CC because the statutory exception depends on the assessee's tax liability. Where no assessment or other tax determination exists, the complaint does not allege tax payable, and a refund claim remains unaddressed, prosecution is misconceived. Wilful failure is also essential: the statutory presumption of culpable mental state may be rebutted through evidence showing no intent to evade tax. Evidence that property was jointly acquired, loan-financed, and that sale consideration was received by the spouse rebutted wilfulness. The convictions and sentences were set aside, and the assessee was acquitted.
Tax payable is material to prosecution for failure to furnish a return under Section 276CC because the statutory exception depends on the assessee's tax liability. Where no assessment or other tax determination exists, the complaint does not allege tax payable, and a refund claim remains unaddressed, prosecution is misconceived. Wilful failure is also essential: the statutory presumption of culpable mental state may be rebutted through evidence showing no intent to evade tax. Evidence that property was jointly acquired, loan-financed, and that sale consideration was received by the spouse rebutted wilfulness. The convictions and sentences were set aside, and the assessee was acquitted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929