Functional, asset and risk analysis excludes diversified technology companies from captive software development comparables under cost-plus arrangemen...
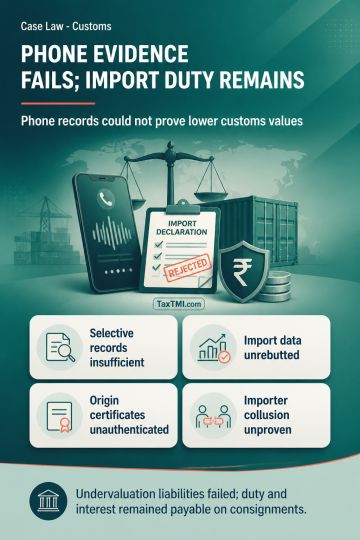
Mobile-phone electronic evidence failed to establish customs undervaluation, while duty survived on non-authentic origin certificates without importer...
Automotive radio classification treats integrated infotainment features as supplementary, placing complete and qualifying unassembled units under the ...
Separate corporate personality prevents directors from being personally liable for company deposits without a guarantee or independent legal undertaki...
Cross-segment derivatives manipulation: integrated order patterns can support interim restraints, while director liability requires responsibility, co...
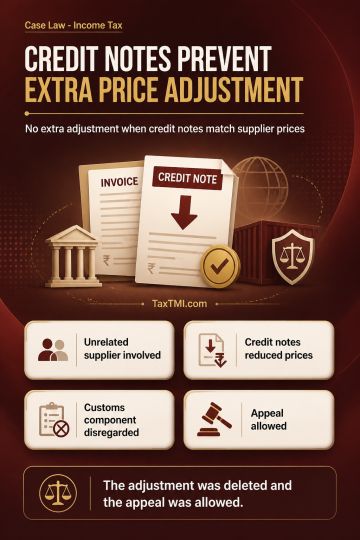
Transfer-pricing adjustment on raw-material purchases routed through a pass-through associated enterprise is not warranted where the unrelated foreign supplier directly supplies the goods and credit notes reduce the effective price to that supplier's price. An additional invoiced component used solely for customs-duty valuation does not justify an arm's length price adjustment in those circumstances. Compliance with the direction concerning operating revenue results in no further adjustment. The transfer-pricing adjustment on these purchases was deleted and the appeal allowed.
Transfer-pricing adjustment on raw-material purchases routed through a pass-through associated enterprise is not warranted where the unrelated foreign supplier directly supplies the goods and credit notes reduce the effective price to that supplier's price. An additional invoiced component used solely for customs-duty valuation does not justify an arm's length price adjustment in those circumstances. Compliance with the direction concerning operating revenue results in no further adjustment. The transfer-pricing adjustment on these purchases was deleted and the appeal allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927