Separate speaking orders on reopening objections are mandatory; deciding them within reassessment invalidates jurisdiction and precludes revival of st...
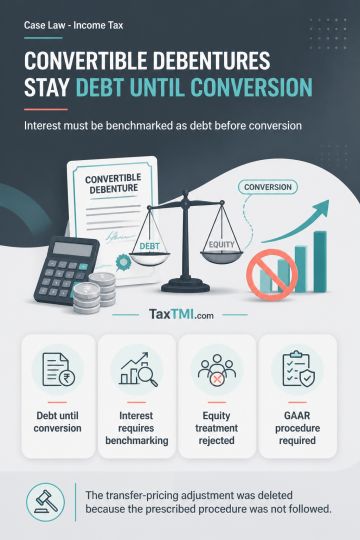
Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
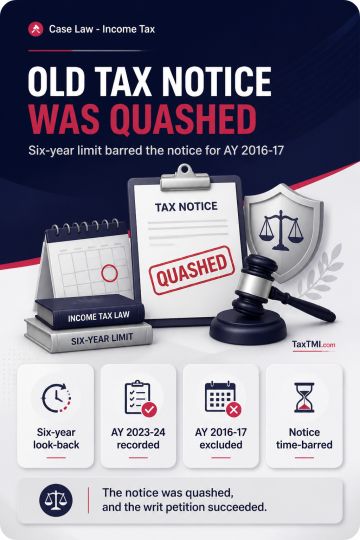
Section 153C limitation requires the six-year look-back period to be calculated from the assessment year immediately preceding the year in which the satisfaction note is recorded. Where the satisfaction note was recorded in AY 2023-24, the period extended only to AY 2017-18; AY 2016-17 lay outside it. The notice for AY 2016-17 was therefore time-barred and quashed, and the writ petition succeeded.
Note: It is a system-generated summary and is for quick reference only.