E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
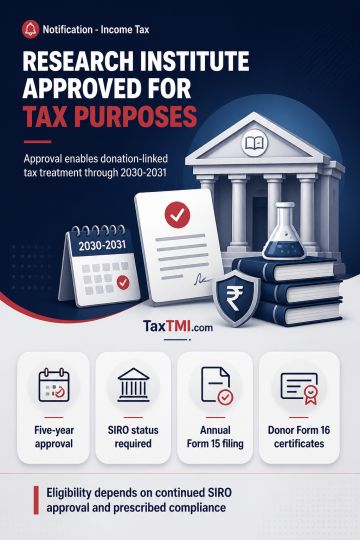
Institute for Financial Management and Research is approved as an institution for social science or statistical research under the university, college or other institution category for the specified Income-tax Act purposes. The approval applies for tax years 2026-2027 through 2030-2031, subject to continued Scientific and Industrial Research Organisation approval in every relevant tax year. The institution must comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the tax year of receipt, and issue donors a Form No. 16 certificate stating the donation amount.
Institute for Financial Management and Research is approved as an institution for social science or statistical research under the university, college or other institution category for the specified Income-tax Act purposes. The approval applies for tax years 2026-2027 through 2030-2031, subject to continued Scientific and Industrial Research Organisation approval in every relevant tax year. The institution must comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the tax year of receipt, and issue donors a Form No. 16 certificate stating the donation amount.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891