Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
Modified returns after business reorganisation must be assessed within pending proceedings, barring parallel scrutiny and consequential transfer prici...
Turnover mismatches under percentage-completion accounting cannot alone establish suppressed income where customer advances remain recorded as liabili...
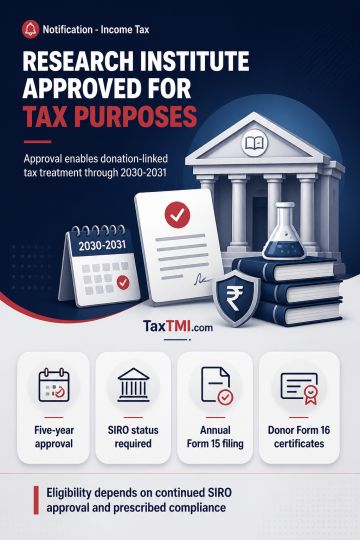
Institute for Financial Management and Research is approved as an institution for social science or statistical research under the university, college or other institution category for the specified Income-tax Act purposes. The approval applies for tax years 2026-2027 through 2030-2031, subject to continued Scientific and Industrial Research Organisation approval in every relevant tax year. The institution must comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the tax year of receipt, and issue donors a Form No. 16 certificate stating the donation amount.
Institute for Financial Management and Research is approved as an institution for social science or statistical research under the university, college or other institution category for the specified Income-tax Act purposes. The approval applies for tax years 2026-2027 through 2030-2031, subject to continued Scientific and Industrial Research Organisation approval in every relevant tax year. The institution must comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the tax year of receipt, and issue donors a Form No. 16 certificate stating the donation amount.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888