Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Page of 4886
Press 'Enter' after typing page number.
441 to 460 of 97714 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
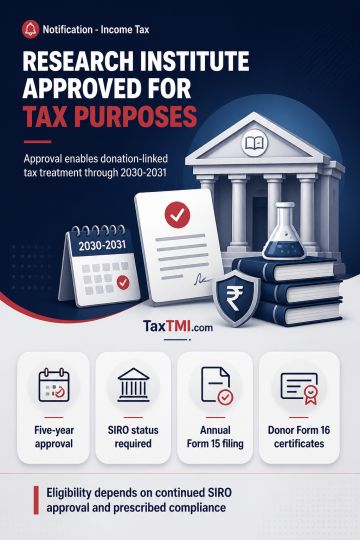
Institute for Financial Management and Research is approved as an institution for social science or statistical research under the university, college or other institution category for the specified Income-tax Act purposes. The approval applies for tax years 2026-2027 through 2030-2031, subject to continued Scientific and Industrial Research Organisation approval in every relevant tax year. The institution must comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the tax year of receipt, and issue donors a Form No. 16 certificate stating the donation amount.
Institute for Financial Management and Research is approved as an institution for social science or statistical research under the university, college or other institution category for the specified Income-tax Act purposes. The approval applies for tax years 2026-2027 through 2030-2031, subject to continued Scientific and Industrial Research Organisation approval in every relevant tax year. The institution must comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the tax year of receipt, and issue donors a Form No. 16 certificate stating the donation amount.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886