Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
Section 54 construction relief survives pre-transfer commencement when completion occurs within the statutory period, excluding ineligible spouse-owne...
Fraud classification show-cause notices founded on inconclusive forensic audit material cannot sustain action, permitting fresh proceedings on conclus...
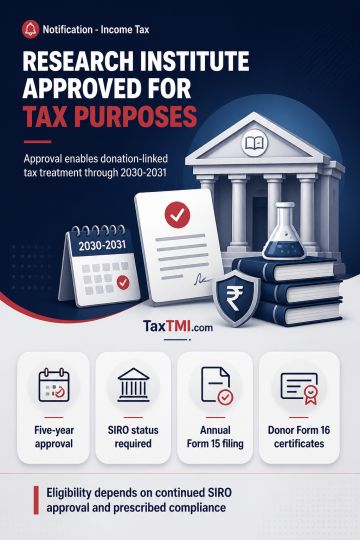
Institute for Financial Management and Research is approved as an institution for social science or statistical research under the university, college or other institution category for the specified Income-tax Act purposes. The approval applies for tax years 2026-2027 through 2030-2031, subject to continued Scientific and Industrial Research Organisation approval in every relevant tax year. The institution must comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the tax year of receipt, and issue donors a Form No. 16 certificate stating the donation amount.
Institute for Financial Management and Research is approved as an institution for social science or statistical research under the university, college or other institution category for the specified Income-tax Act purposes. The approval applies for tax years 2026-2027 through 2030-2031, subject to continued Scientific and Industrial Research Organisation approval in every relevant tax year. The institution must comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the tax year of receipt, and issue donors a Form No. 16 certificate stating the donation amount.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4883