Supervisory permanent establishment requires project-wise duration and qualifying construction nexus; offshore supplies and salary reimbursements rema...
Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
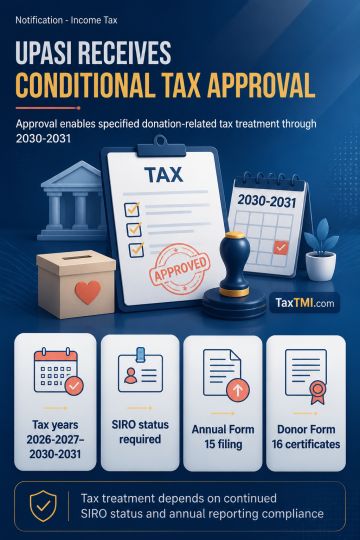
UPASI Tea Research Foundation is approved as an 'Other Institution' for scientific research purposes under the Income-tax Act, enabling the specified donation-related tax treatment. The approval applies for tax years 2026-2027 to 2030-2031 and remains conditional on the foundation retaining Scientific and Industrial Research Organization approval throughout each relevant tax year. It must also comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the relevant tax year, and provide donors with Form No. 16 certificates stating the donation amount.
UPASI Tea Research Foundation is approved as an 'Other Institution' for scientific research purposes under the Income-tax Act, enabling the specified donation-related tax treatment. The approval applies for tax years 2026-2027 to 2030-2031 and remains conditional on the foundation retaining Scientific and Industrial Research Organization approval throughout each relevant tax year. It must also comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the relevant tax year, and provide donors with Form No. 16 certificates stating the donation amount.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4879