Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
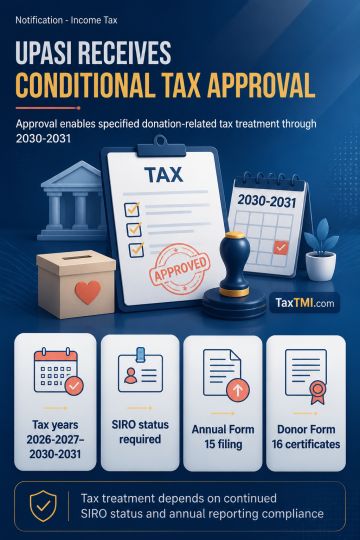
UPASI Tea Research Foundation is approved as an 'Other Institution' for scientific research purposes under the Income-tax Act, enabling the specified donation-related tax treatment. The approval applies for tax years 2026-2027 to 2030-2031 and remains conditional on the foundation retaining Scientific and Industrial Research Organization approval throughout each relevant tax year. It must also comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the relevant tax year, and provide donors with Form No. 16 certificates stating the donation amount.
UPASI Tea Research Foundation is approved as an 'Other Institution' for scientific research purposes under the Income-tax Act, enabling the specified donation-related tax treatment. The approval applies for tax years 2026-2027 to 2030-2031 and remains conditional on the foundation retaining Scientific and Industrial Research Organization approval throughout each relevant tax year. It must also comply with prescribed conditions, submit an annual donation statement in Form No. 15 by 31 May following the relevant tax year, and provide donors with Form No. 16 certificates stating the donation amount.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881