Non-participating bidders cannot disturb concluded liquidation sales on speculative prejudice, while costs for such challenges must remain proportiona...
Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
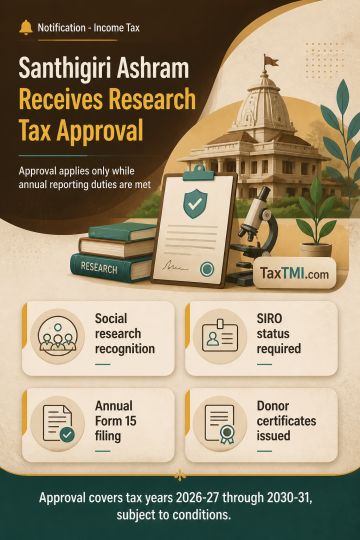
Santhigiri Ashram is approved as a university, college or other institution for social science or statistical research under the Income-tax Act, 2025, for tax years 2026-27 to 2030-31. The approval requires continuing Scientific and Industrial Research Organisation status in each effective tax year, compliance with rule 34, annual Form 15 donation statements delivered by 31 May following the tax year in which donations are received, and Form 16 donation certificates issued to donors.
Santhigiri Ashram is approved as a university, college or other institution for social science or statistical research under the Income-tax Act, 2025, for tax years 2026-27 to 2030-31. The approval requires continuing Scientific and Industrial Research Organisation status in each effective tax year, compliance with rule 34, annual Form 15 donation statements delivered by 31 May following the tax year in which donations are received, and Form 16 donation certificates issued to donors.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897