Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
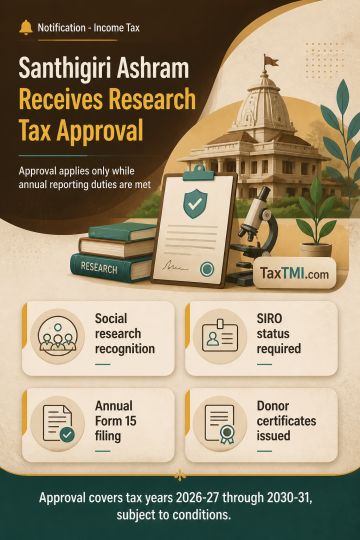
Santhigiri Ashram is approved as a university, college or other institution for social science or statistical research under the Income-tax Act, 2025, for tax years 2026-27 to 2030-31. The approval requires continuing Scientific and Industrial Research Organisation status in each effective tax year, compliance with rule 34, annual Form 15 donation statements delivered by 31 May following the tax year in which donations are received, and Form 16 donation certificates issued to donors.
Santhigiri Ashram is approved as a university, college or other institution for social science or statistical research under the Income-tax Act, 2025, for tax years 2026-27 to 2030-31. The approval requires continuing Scientific and Industrial Research Organisation status in each effective tax year, compliance with rule 34, annual Form 15 donation statements delivered by 31 May following the tax year in which donations are received, and Form 16 donation certificates issued to donors.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888