Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
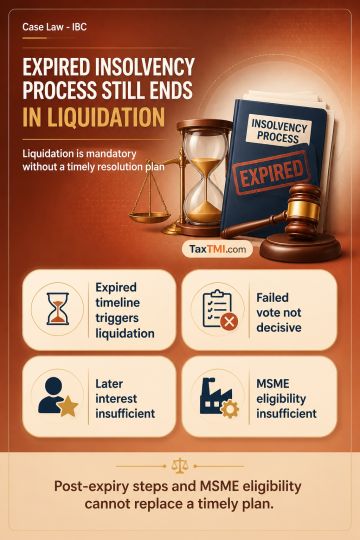
Section 33(1)(a) requires liquidation when the CIRP expires without a resolution plan submitted under Section 30(6) or a valid extension. This consequence operates independently of liquidation initiated through a Committee of Creditors resolution under Section 33(2); failure of that separate proposal to receive the required vote does not prevent liquidation. The Committee's commercial wisdom remains subject to statutory CIRP timelines and cannot revive an expired process. Post-expiry directions, later expressions of interest, and MSME eligibility cannot replace a resolution plan submitted and processed within the prescribed period.
Section 33(1)(a) requires liquidation when the CIRP expires without a resolution plan submitted under Section 30(6) or a valid extension. This consequence operates independently of liquidation initiated through a Committee of Creditors resolution under Section 33(2); failure of that separate proposal to receive the required vote does not prevent liquidation. The Committee's commercial wisdom remains subject to statutory CIRP timelines and cannot revive an expired process. Post-expiry directions, later expressions of interest, and MSME eligibility cannot replace a resolution plan submitted and processed within the prescribed period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881