Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
Page of 4931
Press 'Enter' after typing page number.
921 to 940 of 98613 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
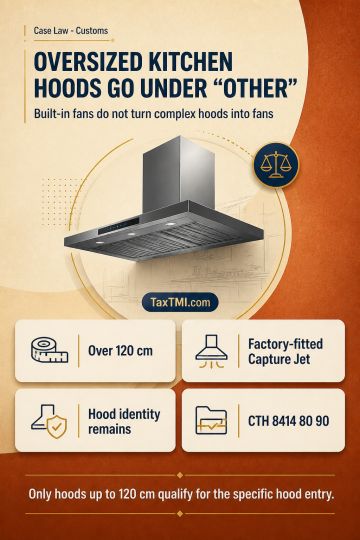
Kitchen exhaust hoods exceeding a 120 cm maximum horizontal side and incorporating factory-fitted Capture Jet fans are classified under CTH 8414 80 90 as "Other", rather than as fans under CTH 8414 59 90. Heading 8414 separately identifies fans and ventilating or recycling hoods incorporating a fan. An integral fan does not change a structurally complex hood assembly's essential character where its components and market identity remain those of a hood. The specific hood entry under CTH 8414 60 00 applies only where the maximum horizontal side does not exceed 120 cm.
Kitchen exhaust hoods exceeding a 120 cm maximum horizontal side and incorporating factory-fitted Capture Jet fans are classified under CTH 8414 80 90 as "Other", rather than as fans under CTH 8414 59 90. Heading 8414 separately identifies fans and ventilating or recycling hoods incorporating a fan. An integral fan does not change a structurally complex hood assembly's essential character where its components and market identity remain those of a hood. The specific hood entry under CTH 8414 60 00 applies only where the maximum horizontal side does not exceed 120 cm.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931