Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
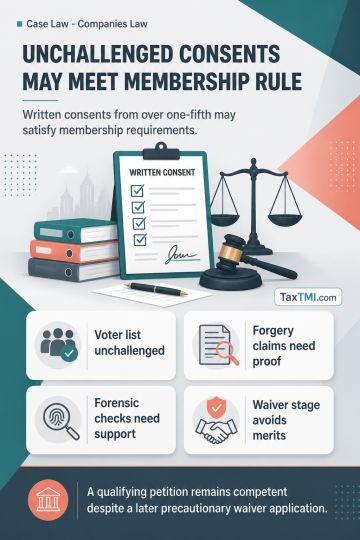
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
GST show cause notices initiate, rather than conclusively determine, tax liability. Statutory adjudication must consider the registered person's reply; recording the reply as unsatisfactory does not preclude independent examination of whether it received adequate consideration. Objections concerning audit findings, limitation, tax computation and treatment of deposits fall for determination by the Adjudicating Authority. Writ intervention should not ordinarily pre-empt that statutory process, and substantive objections remain available during adjudication.
GST show cause notices initiate, rather than conclusively determine, tax liability. Statutory adjudication must consider the registered person's reply; recording the reply as unsatisfactory does not preclude independent examination of whether it received adequate consideration. Objections concerning audit findings, limitation, tax computation and treatment of deposits fall for determination by the Adjudicating Authority. Writ intervention should not ordinarily pre-empt that statutory process, and substantive objections remain available during adjudication.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935