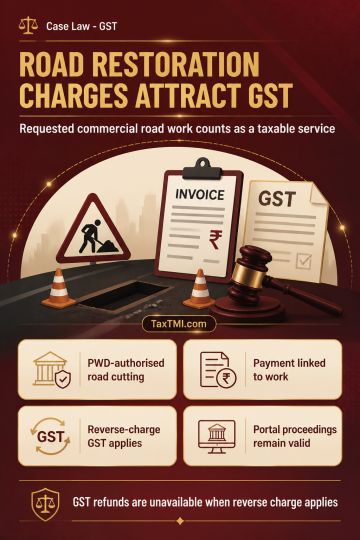
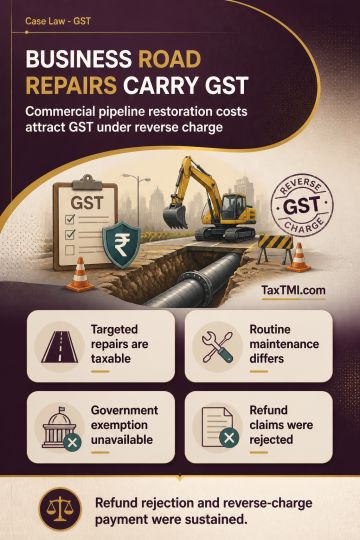
Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
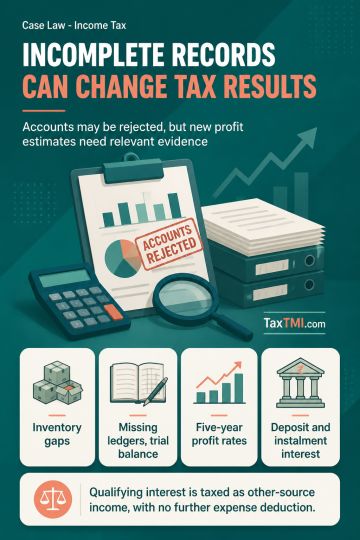
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
GST show cause notices initiate, rather than conclusively determine, tax liability. Statutory adjudication must consider the registered person's reply; recording the reply as unsatisfactory does not preclude independent examination of whether it received adequate consideration. Objections concerning audit findings, limitation, tax computation and treatment of deposits fall for determination by the Adjudicating Authority. Writ intervention should not ordinarily pre-empt that statutory process, and substantive objections remain available during adjudication.
GST show cause notices initiate, rather than conclusively determine, tax liability. Statutory adjudication must consider the registered person's reply; recording the reply as unsatisfactory does not preclude independent examination of whether it received adequate consideration. Objections concerning audit findings, limitation, tax computation and treatment of deposits fall for determination by the Adjudicating Authority. Writ intervention should not ordinarily pre-empt that statutory process, and substantive objections remain available during adjudication.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937