Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
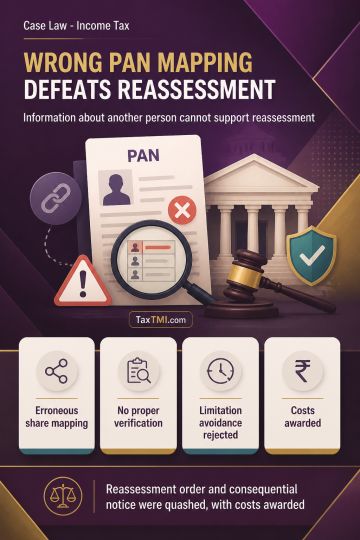
Reassessment founded on a share transaction wrongly mapped to an assessee's PAN is unsustainable where the underlying information concerns another person. Initiating proceedings without verification merely to avoid limitation constitutes a colourable exercise of reassessment power. The reassessment order and consequential notice were quashed, and costs were awarded in the proceedings.
Reassessment founded on a share transaction wrongly mapped to an assessee's PAN is unsustainable where the underlying information concerns another person. Initiating proceedings without verification merely to avoid limitation constitutes a colourable exercise of reassessment power. The reassessment order and consequential notice were quashed, and costs were awarded in the proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931