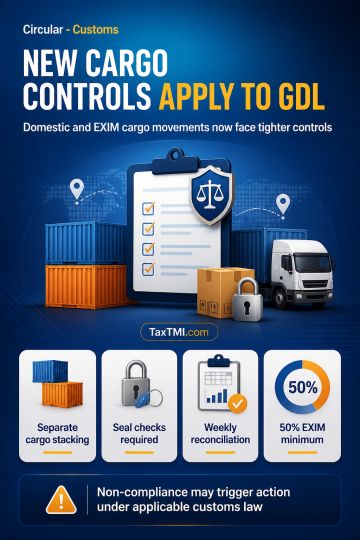
Customs-controlled cargo movement now includes GDL, subject to EXIM prioritisation, segregation, verification, reconciliation and enforcement safeguar...
GST cross-empowerment remains effective without conditional notification, while duplicate proceedings require established safeguards against overlappi...
Page of 4939
Press 'Enter' after typing page number.
1221 to 1240 of 98775 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Service of a GST show-cause notice solely through upload on the Common Portal may be inadequate where receipt is unacknowledged, no reply is filed, and the taxpayer lacks effective knowledge of the proceedings. Although the statutory limitation period binds the appellate authority, writ jurisdiction may address delay caused by circumstances beyond the taxpayer's control where refusing merits adjudication would cause grave injury or prejudice. In the stated circumstances, delay in filing the GST appeal against an input tax credit demand was condoned, the limitation-based dismissal was set aside, and the appellate authority was directed to decide the fresh appeal on merits without raising limitation.
Service of a GST show-cause notice solely through upload on the Common Portal may be inadequate where receipt is unacknowledged, no reply is filed, and the taxpayer lacks effective knowledge of the proceedings. Although the statutory limitation period binds the appellate authority, writ jurisdiction may address delay caused by circumstances beyond the taxpayer's control where refusing merits adjudication would cause grave injury or prejudice. In the stated circumstances, delay in filing the GST appeal against an input tax credit demand was condoned, the limitation-based dismissal was set aside, and the appellate authority was directed to decide the fresh appeal on merits without raising limitation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4939