Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adju...
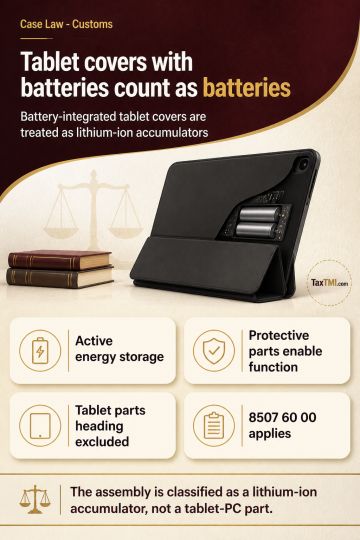
Battery-integrated tablet rear covers classify as lithium-ion accumulators when protective components enable the battery's active energy-storage funct...
Service of a GST show-cause notice solely through upload on the Common Portal may be inadequate where receipt is unacknowledged, no reply is filed, and the taxpayer lacks effective knowledge of the proceedings. Although the statutory limitation period binds the appellate authority, writ jurisdiction may address delay caused by circumstances beyond the taxpayer's control where refusing merits adjudication would cause grave injury or prejudice. In the stated circumstances, delay in filing the GST appeal against an input tax credit demand was condoned, the limitation-based dismissal was set aside, and the appellate authority was directed to decide the fresh appeal on merits without raising limitation.
Service of a GST show-cause notice solely through upload on the Common Portal may be inadequate where receipt is unacknowledged, no reply is filed, and the taxpayer lacks effective knowledge of the proceedings. Although the statutory limitation period binds the appellate authority, writ jurisdiction may address delay caused by circumstances beyond the taxpayer's control where refusing merits adjudication would cause grave injury or prejudice. In the stated circumstances, delay in filing the GST appeal against an input tax credit demand was condoned, the limitation-based dismissal was set aside, and the appellate authority was directed to decide the fresh appeal on merits without raising limitation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897