Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
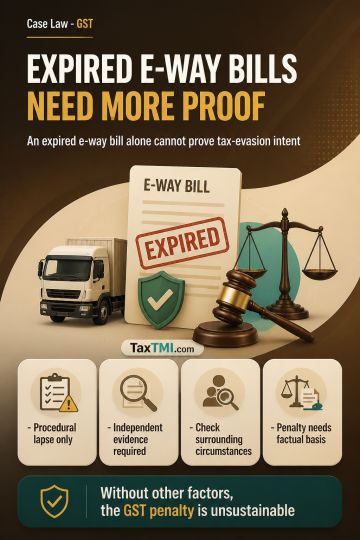
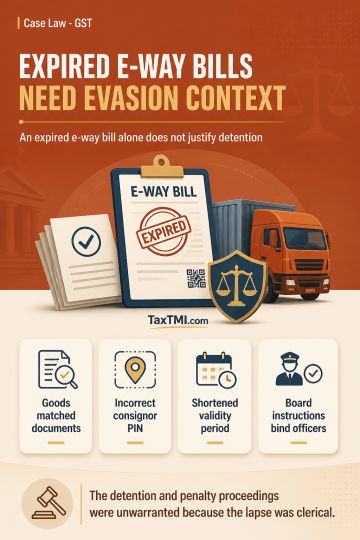
Section 129 penalty for an expired e-way bill must serve its tax-evasion prevention purpose, notwithstanding that the provision does not expressly require mens rea. Board instructions identifying situations in which section 129 need not be invoked bind the proper officer. Where goods matched the e-way bill and delivery challan, and an erroneous consignor PIN code shortened rather than extended validity, the lapse was clerical. Without any allegation of intent to evade tax, detention and penalty proceedings under section 129 were unwarranted.
Section 129 penalty for an expired e-way bill must serve its tax-evasion prevention purpose, notwithstanding that the provision does not expressly require mens rea. Board instructions identifying situations in which section 129 need not be invoked bind the proper officer. Where goods matched the e-way bill and delivery challan, and an erroneous consignor PIN code shortened rather than extended validity, the lapse was clerical. Without any allegation of intent to evade tax, detention and penalty proceedings under section 129 were unwarranted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927