Final benami adjudication bars contradictory tax-evasion prosecution where settlement findings confirm full disclosure and cooperation without conceal...
Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
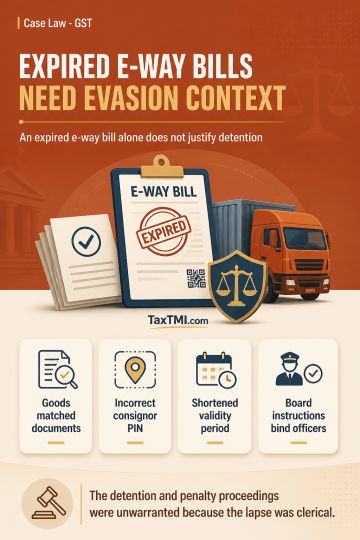
Section 129 penalty for an expired e-way bill must serve its tax-evasion prevention purpose, notwithstanding that the provision does not expressly require mens rea. Board instructions identifying situations in which section 129 need not be invoked bind the proper officer. Where goods matched the e-way bill and delivery challan, and an erroneous consignor PIN code shortened rather than extended validity, the lapse was clerical. Without any allegation of intent to evade tax, detention and penalty proceedings under section 129 were unwarranted.
Section 129 penalty for an expired e-way bill must serve its tax-evasion prevention purpose, notwithstanding that the provision does not expressly require mens rea. Board instructions identifying situations in which section 129 need not be invoked bind the proper officer. Where goods matched the e-way bill and delivery challan, and an erroneous consignor PIN code shortened rather than extended validity, the lapse was clerical. Without any allegation of intent to evade tax, detention and penalty proceedings under section 129 were unwarranted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888