Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Merchant-export concession requires direct movement; disclosed supplies face non-fraud GST demand while undisclosed supplies retain fraud-based liabil...
    Section 74 suppression demands require pleaded foundational facts, while undisclosed rental income supports extended-period GST liability.
    Zero-rated export turnover includes invoices issued in the refund period even where goods are exported later.
    Actual receipt of goods governs input tax credit, while duplicate penalties require statutory justification and procedural fairness.
    Technical e-way bill discrepancies cannot support GST penalties where transactions are reported, tax paid, and evasion intent is absent.
    Prospective refund restrictions cannot defeat pre-existing input tax credit claims merely because the refund application was filed later.
    Statutory GST appeal limits bar excess delay condonation, while restoring registration prevents departmental challenge to the implemented order.
    Limitation for Tribunal appeals begins on receipt of the reasoned order, while sufficient cause can justify condonation.
    Refund adjustment during pending tax appeals requires prior intimation and binding recovery instructions; improper recovery attracts interest-bearing ...
    Joint development transfer triggers capital gains for property-owning association, while valuation must reflect consideration at the transfer date.
    Book rejection for missing stock records requires rational profit estimation and fresh cash-credit verification, with reassessment directed.
    Characterisation of flat-sale receipts as business income defeats capital-gains treatment and the residential-property reinvestment deduction.
    Inter-bank transfers from disclosed salary income are not unexplained money; rental income retains the statutory standard deduction.
    GST turnover reconciliation prevents gross-profit additions where duplicate reporting, rather than off-book sales, explains the reported turnover diff...
    Reasonable cause for delayed compliance with tax notices can preclude penalties where reassessment concludes after substantive replies.
    Mandatory limitation for final assessments runs from electronic directions under the special statutory timeline, overriding general assessment time li...
    Compensatory land allotment requires verification before deemed-property income taxation and under-reporting penalty can be sustained.
    Managing director performance commission qualifies as deductible remuneration where it reflects services, salary taxation, declared dividends, and con...
    Commercial exploitation of leasehold rights makes sub-letting receipts business income where ancillary services form part of the arrangement.
    Concealment penalty on estimated bogus-purchase additions is unsustainable where the disallowance rests solely on an ad hoc basis.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Telegram Get Daily Updates

Government-supported Exim Bank Line of Credit supports financing...

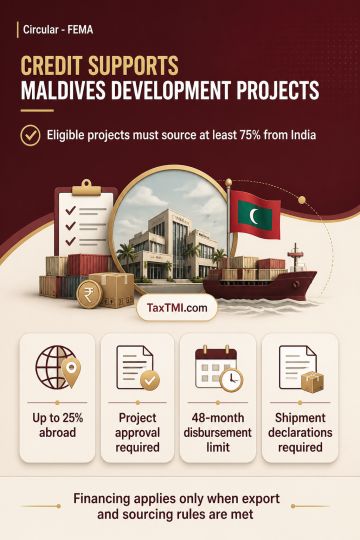
GOI-supported Line of Credit enables eligible Indian exports for Maldives projects subject to domestic sourcing and export conditions.

Contents
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

FEMA September 28, 2026 Circulars
Government-supported Exim Bank Line of Credit supports financing of developmental projects in Maldives through eligible Indian exports that comply with the Foreign Trade Policy and financing terms. At least 75% of each eligible contract's goods, works and services must be supplied from India, while up to 25% may be sourced abroad. Individual credit agreements require project identification and approval. Disbursement ends 48 months after scheduled contract completion. Exporters must declare shipments through export declaration forms or shipping bills; agency commission is not payable under the facility.

Topics

Acts Income Tax