Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adju...
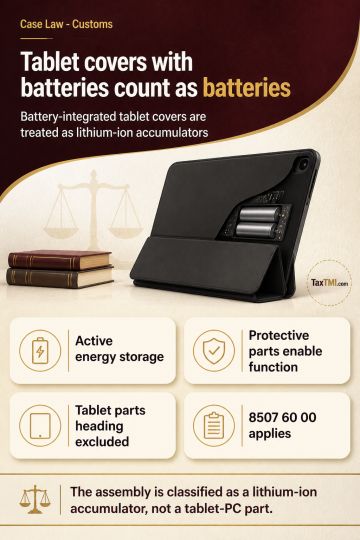
Battery-integrated tablet rear covers classify as lithium-ion accumulators when protective components enable the battery's active energy-storage funct...
Rule 11UA(2) permits an assessee issuing unquoted equity shares to choose either the Discounted Cash Flow or Net Asset Value method for determining fair market value under section 56(2)(viib). After a prescribed method is chosen, the Assessing Officer may scrutinise the valuation report but cannot replace it with a formula-based valuation merely because projections, management inputs, or standard disclaimers are questioned. Discounted Cash Flow projections cannot be rejected solely by comparison with subsequent performance. Rejection requires demonstrably incorrect data, a wholly erroneous basis, or a wrong valuation approach; absent such defects, the chosen method governs share-premium valuation.
Rule 11UA(2) permits an assessee issuing unquoted equity shares to choose either the Discounted Cash Flow or Net Asset Value method for determining fair market value under section 56(2)(viib). After a prescribed method is chosen, the Assessing Officer may scrutinise the valuation report but cannot replace it with a formula-based valuation merely because projections, management inputs, or standard disclaimers are questioned. Discounted Cash Flow projections cannot be rejected solely by comparison with subsequent performance. Rejection requires demonstrably incorrect data, a wholly erroneous basis, or a wrong valuation approach; absent such defects, the chosen method governs share-premium valuation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881