Appellate enhancement limits protect against new income sources, while documented credits and prior-year investments resist unexplained-income additio...
Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
Page of 4868
Press 'Enter' after typing page number.
1 to 20 of 97344 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
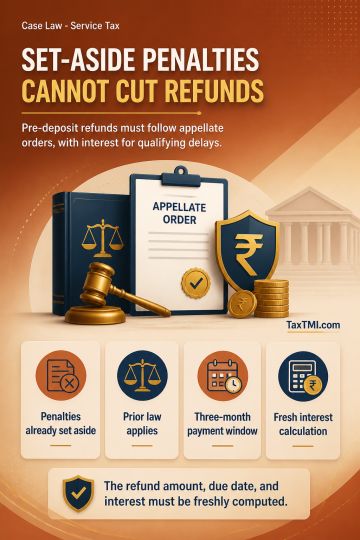
Refunds of pre-deposit arising from appellate relief must be determined under the appellate order; penalties already set aside cannot be recovered by appropriating the refund, and setting aside the Event Management Services demand makes the corresponding deposit refundable. For appeals pending when the statutory amendment took effect, the unamended Section 35FF regime applies. Interest on delayed pre-deposit refund accrues only if payment is not made within three months of the jurisdictional authority receiving the appellate order. The refund amount, due date and consequential interest require fresh computation.
Refunds of pre-deposit arising from appellate relief must be determined under the appellate order; penalties already set aside cannot be recovered by appropriating the refund, and setting aside the Event Management Services demand makes the corresponding deposit refundable. For appeals pending when the statutory amendment took effect, the unamended Section 35FF regime applies. Interest on delayed pre-deposit refund accrues only if payment is not made within three months of the jurisdictional authority receiving the appellate order. The refund amount, due date and consequential interest require fresh computation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI