Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adju...
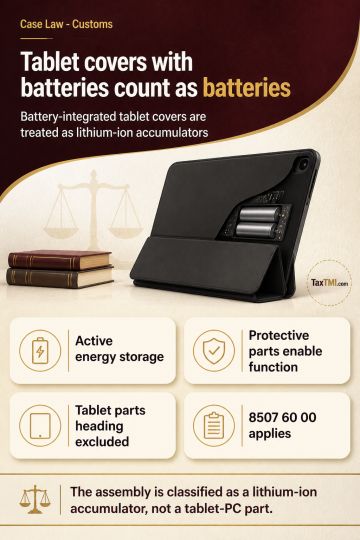
Battery-integrated tablet rear covers classify as lithium-ion accumulators when protective components enable the battery's active energy-storage funct...
Dismissal of a duly constituted GST first appeal for non-prosecution, despite pre-deposit and alleged inadequate notice of hearing, should not leave the appellant remediless or compel a second appeal. Statutory procedure permits the Appellate Tribunal to dismiss an appeal for default and set aside that dismissal. High Court set aside the dismissal where there was no apparent reason for the appellant to abandon its appeal after making the pre-deposit, and remanded the matter to the Appellate Authority for fresh adjudication after due opportunity of hearing.
Dismissal of a duly constituted GST first appeal for non-prosecution, despite pre-deposit and alleged inadequate notice of hearing, should not leave the appellant remediless or compel a second appeal. Statutory procedure permits the Appellate Tribunal to dismiss an appeal for default and set aside that dismissal. High Court set aside the dismissal where there was no apparent reason for the appellant to abandon its appeal after making the pre-deposit, and remanded the matter to the Appellate Authority for fresh adjudication after due opportunity of hearing.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881