Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adju...
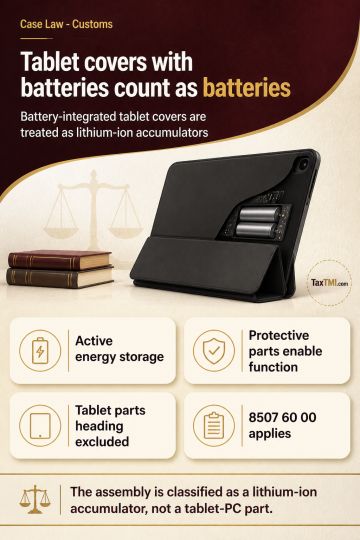
Battery-integrated tablet rear covers classify as lithium-ion accumulators when protective components enable the battery's active energy-storage funct...
Section 50B prescribes a self-contained method for computing capital gains on a slump sale, including fair market value and net worth under Rule 11UAE. Where no defect in the valuation methodology or non-compliance with Rule 11UAE is identified, the Assessing Officer cannot substitute a different valuation; deletion of the resulting capital-gains addition was confirmed. A capital-gains addition made without a proper show-cause notice also breached CBDT Instruction No. 20/2015 and was independently unsustainable. The Revenue's appeal was dismissed.
Section 50B prescribes a self-contained method for computing capital gains on a slump sale, including fair market value and net worth under Rule 11UAE. Where no defect in the valuation methodology or non-compliance with Rule 11UAE is identified, the Assessing Officer cannot substitute a different valuation; deletion of the resulting capital-gains addition was confirmed. A capital-gains addition made without a proper show-cause notice also breached CBDT Instruction No. 20/2015 and was independently unsustainable. The Revenue's appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4884