Customs exemptions cover photovoltaic assembly machinery and PVF backsheets, while fully declared cleared imports may avoid confiscation and penalties...
Specific tariff classification for LCD devices overrides treatment as electricity-meter parts, defeating differential duty, extended limitation, and p...
Stayed disciplinary punishment does not establish unfitness for insolvency professional registration; reconsideration must disregard mere pendency of ...
Indirect corporate control can create related-party status, excluding financial creditors from Committee of Creditors representation, participation an...
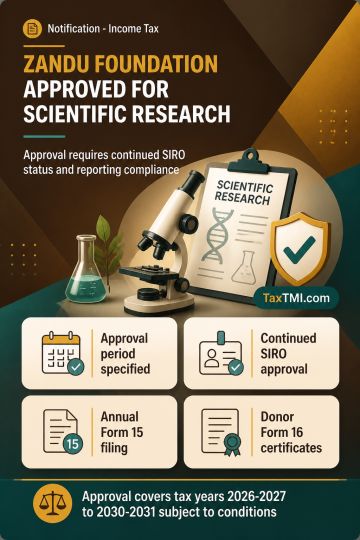
Scientific research association approval requires continuing SIRO status, annual donation reporting, and donor certificates for the approved foundatio...
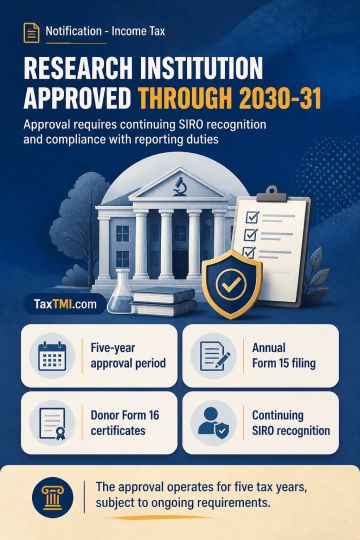
Scientific research institution approval is conditional on SIRO recognition, annual donation reporting, donor certification, and prescribed compliance...
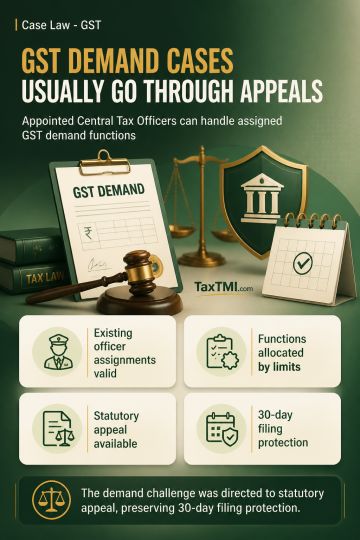
Proper-officer functions under the CGST Act may be assigned by circular to Central Tax Officers already appointed under a statutory notification, including demand-related functions allocated by monetary limits. Such assignment does not constitute delegation requiring a separate notification. Challenges to the circulars and to the officer's competence on that basis were rejected. A writ challenge to a GST demand order should ordinarily not proceed where an effective statutory appeal is available, unless a recognised exception applies. Where the authority considered the defence, examined documents and granted a personal hearing, reassessment of disputed material lies with the appellate authority. The demand challenge was therefore directed to the statutory appeal, with limitation protection for filing within 30 days.
Proper-officer functions under the CGST Act may be assigned by circular to Central Tax Officers already appointed under a statutory notification, including demand-related functions allocated by monetary limits. Such assignment does not constitute delegation requiring a separate notification. Challenges to the circulars and to the officer's competence on that basis were rejected. A writ challenge to a GST demand order should ordinarily not proceed where an effective statutory appeal is available, unless a recognised exception applies. Where the authority considered the defence, examined documents and granted a personal hearing, reassessment of disputed material lies with the appellate authority. The demand challenge was therefore directed to the statutory appeal, with limitation protection for filing within 30 days.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4934