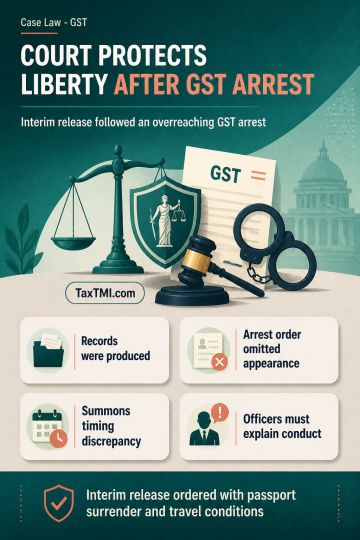
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
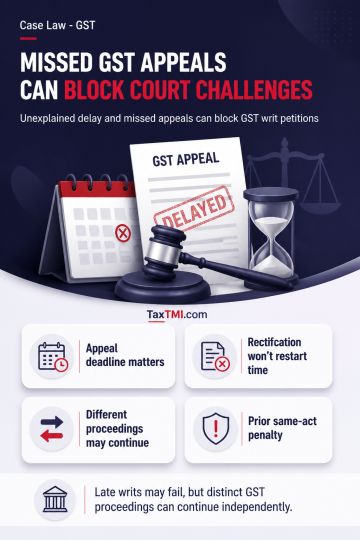
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
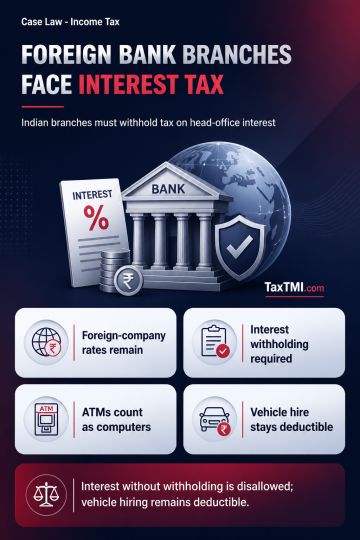
Article 24(2) of the India-Netherlands DTAA does not entitle an Indian permanent establishment of a Netherlands bank to domestic-company tax rates where it remains a foreign company; the section 90 Explanation treats a higher foreign-company rate as non-discriminatory. Article 7's separate-enterprise fiction requires consistent treatment: interest remitted by an Indian PE to its overseas head office or branches is taxable in India, requires withholding, and is disallowed if withholding fails; interest received from them is taxable PE business income. ATMs qualify as computers for depreciation based on functional utility. Accounting Standard 19 does not govern tax characterisation; vehicle hiring payments remain deductible revenue expenditure absent an intention to acquire ownership.
Article 24(2) of the India-Netherlands DTAA does not entitle an Indian permanent establishment of a Netherlands bank to domestic-company tax rates where it remains a foreign company; the section 90 Explanation treats a higher foreign-company rate as non-discriminatory. Article 7's separate-enterprise fiction requires consistent treatment: interest remitted by an Indian PE to its overseas head office or branches is taxable in India, requires withholding, and is disallowed if withholding fails; interest received from them is taxable PE business income. ATMs qualify as computers for depreciation based on functional utility. Accounting Standard 19 does not govern tax characterisation; vehicle hiring payments remain deductible revenue expenditure absent an intention to acquire ownership.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932