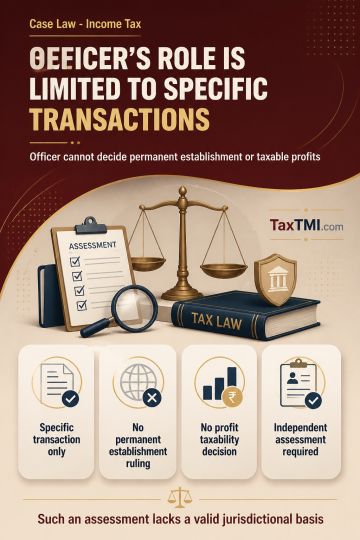
Transfer Pricing Officer jurisdiction is transaction-specific, excluding permanent establishment determinations and requiring independent assessment o...
Rental income valuation requires credible local comparables; family-business salary and commercially expedient unsecured-loan interest remained deduct...
Regular bail in an alleged fraudulent input tax credit offence under the CGST Act was granted after the charge sheet was filed. Continued pre-trial detention was considered unnecessary because the accused had remained in custody, no flight risk or criminal antecedents were shown, further custodial detention was not required, and the maximum punishment was five years. Bail was subject to stringent conditions requiring cooperation in the ongoing investigation and trial involving co-accused, attendance, and non-interference with proceedings.
Regular bail in an alleged fraudulent input tax credit offence under the CGST Act was granted after the charge sheet was filed. Continued pre-trial detention was considered unnecessary because the accused had remained in custody, no flight risk or criminal antecedents were shown, further custodial detention was not required, and the maximum punishment was five years. Bail was subject to stringent conditions requiring cooperation in the ongoing investigation and trial involving co-accused, attendance, and non-interference with proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881