Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
    Sequential Customs Valuation Requires Comparable Imports Review Before Residual Valuation and Undervaluation Demands Can Stand
    Cross-examination of relied-upon witnesses is mandatory before imposing Customs Broker penalties, requiring fresh adjudication where denied.
    Classification of oven-roasted nuts distinguishes roasting from drying and applies specific entries, while preference requires origin verification.
    Battery-integrated tablet rear covers classify as lithium-ion accumulators when protective components enable the battery's active energy-storage funct...
    Documentary customs evasion investigation supported conditional bail where tampering risk was unsubstantiated and cooperation safeguards protected inq...
    Distinct Commodity Classification prevents Furnace Oil from attracting the tariff rate prescribed for Light Diesel Oil.
    Scientific research approval enables donor-related tax treatment, subject to annual reporting, regulatory compliance, and donation certificates.
    Tariff-rate quota surrender deadline extends, allowing raw sugar import holders to relinquish unused allocations subject to prescribed CIF-value payme...
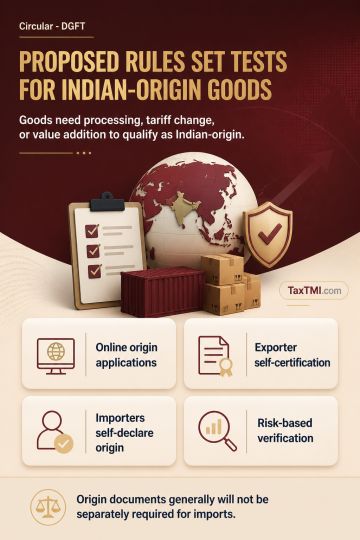
    Non-Preferential Origin Rules propose processing, tariff-change or value-addition tests and importer self-declaration for customs clearance.
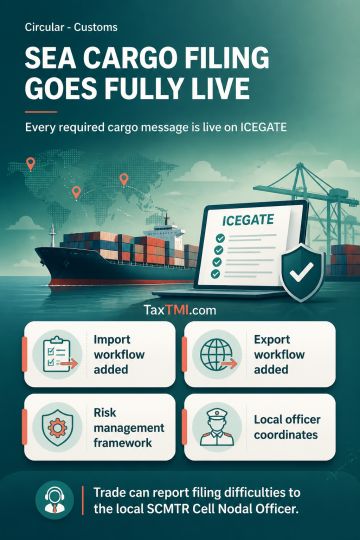
    Sea cargo manifest digital filing is fully operational, enabling live import and export SCMTR message submission through ICEGATE.
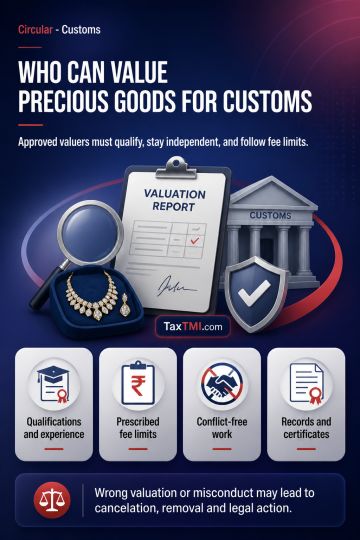
    Customs valuer empanelment sets eligibility, fee controls, independence duties and misconduct consequences for precious-goods valuation services.
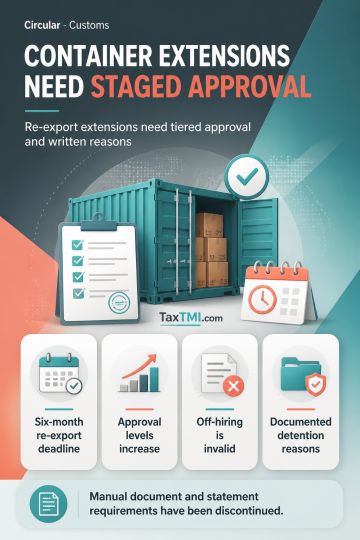
    Container re-export extensions follow a tiered approval process; off-hiring is invalid, while detention-related requests require documented reasons.
    Common Portal Service requires accessible full GST communications and meaningful hearing before limitation or recovery consequences follow.
    Tax rebate on total income extends to short-term capital gains taxed at special rates without express exclusion.
    Inter-State transit goods cannot be detained by GST authorities of a State merely because they pass through its territory.
    Alternative GST remedies limit writ review where registration-cancellation disputes require factual examination by appellate authorities.
    Retrospective input tax credit limitation extension protects eligible belated claims and requires reversal of time-barred credit disallowance.
    Defective GST portal service justified condonation of delay, requiring the appellate authority to hear the appeal on merits.
    Sufficient cause for delayed GST appeals permits merits review where portal placement prevented effective notice.
    Conditional pre-deposit enables fresh adjudication after non-participation and expiry of appellate limitation, subject to a timely reply.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Printing on paper and content owned by a GST-registered customer...

Printing on customer-owned inputs qualifies under Heading 9988, while printer-supplied religious book printing attracts residual-rate GST.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

GST September 23, 2026 Case Laws AAR
Printing on paper and content owned by a GST-registered customer constitutes job work under Heading 9988; where the customer is unregistered, it is a service of treatment or processing of goods belonging to another person under the same heading. Concessional GST treatment applies only to specified printing and to qualifying goods under Chapters 48 or 49 that themselves attract the prescribed concessional or nil rate; other printing services fall under residual entries. Printing religious books using the printer's paper and consumables is a composite supply in which printing is the principal supply. It is classifiable as a printing service under Heading 9989, rather than as a supply of printed books, and attracts the residual GST rate.

Topics

Acts Income Tax