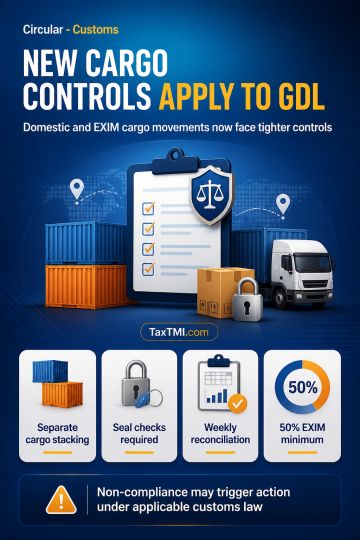
Customs-controlled cargo movement now includes GDL, subject to EXIM prioritisation, segregation, verification, reconciliation and enforcement safeguar...
GST cross-empowerment remains effective without conditional notification, while duplicate proceedings require established safeguards against overlappi...
Page of 4939
Press 'Enter' after typing page number.
1221 to 1240 of 98775 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
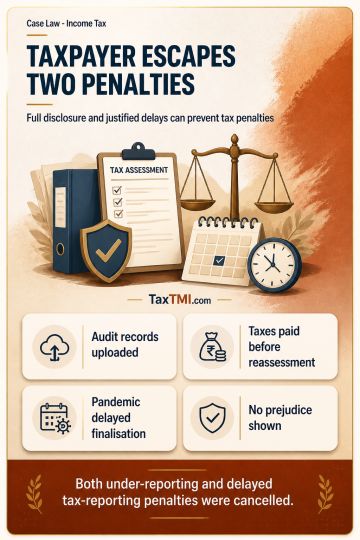
Penalty for under-reported income is excluded where the taxpayer provides a bona fide explanation and fully discloses supporting material facts. Uploading audit records, paying relevant taxes before reassessment, and filing income accepted without additions supported cancellation under section 270A. Delayed tax-audit reporting does not attract penalty where reasonable cause is established: director disputes during the pandemic delayed account finalisation, while prompt upload after finalisation and absence of prejudice supported cancellation under section 271B.
Penalty for under-reported income is excluded where the taxpayer provides a bona fide explanation and fully discloses supporting material facts. Uploading audit records, paying relevant taxes before reassessment, and filing income accepted without additions supported cancellation under section 270A. Delayed tax-audit reporting does not attract penalty where reasonable cause is established: director disputes during the pandemic delayed account finalisation, while prompt upload after finalisation and absence of prejudice supported cancellation under section 271B.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4939