Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
    Functional characterisation of spare replacement services supports TNMM over RPM where customer and resale-price control are absent.
    Modified returns after business reorganisation must be assessed within pending proceedings, barring parallel scrutiny and consequential transfer prici...
    Information suggesting income escapement cannot support reassessment where it merely seeks verification through a roving inquiry.
    Valid reassessment information excludes demerger receipts already taxed by resulting company, defeating extended limitation for reassessment.
    Service of reassessment notices to inactive contact details requires renewed response opportunity before consequential proceedings can stand.
    Alternative concession on agricultural-loss disallowance barred a subsequent challenge to the accepted disallowance in appellate proceedings.
    Reassessment safeguards require independent inquiry, compliance with approved insolvency plans, third-party disclosure, and statutory limitation.
    Functional and financial comparability excludes companies lacking verifiable disclosures, similar business profiles, or qualifying employee costs.
    Turnover mismatches under percentage-completion accounting cannot alone establish suppressed income where customer advances remain recorded as liabili...
    Electronic DRP directions trigger final assessment limitation, rendering assessments completed after the statutory period time-barred and void.
    Permissive possession under a development agreement does not trigger capital gains transfer where it is limited to construction.
    Software development comparability requires employee-cost filtering and segmental data; unsupported CUP receivables interest adjustments fail.
    Modified returns under unilateral advance pricing agreements require pending assessments to conform to agreed transfer-pricing terms.
    Settled tariff classification bars renewed duty drawback misclassification notices for nuts, bolts, washers, hand tools and allied goods.
    Animal feed premix classification places vitamin and enzyme mixtures within animal-feed preparations rather than chemical or enzyme headings.
    Section 108 statements in gold-smuggling cases require cross-examination and corroboration, sustaining liability while enabling lower penalties.
    Tariff classification of refractory mortar excludes the chromium ore heading, eliminating export duty and related penalties.
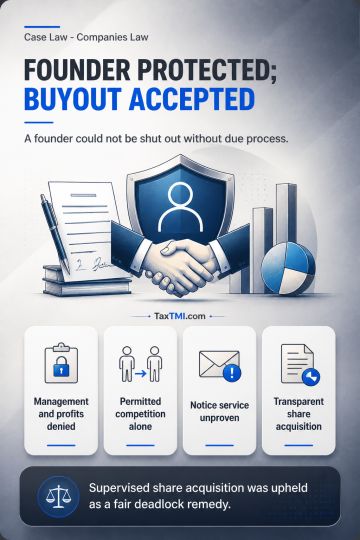
    Oppression in quasi-partnership companies protects excluded founders, while Swiss Challenge buyouts can validly resolve irretrievable shareholder dead...
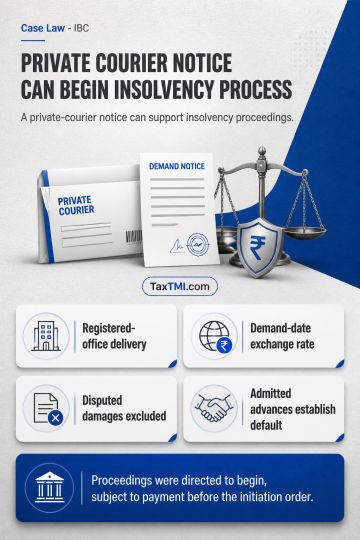
    Private-courier service validates an insolvency demand notice when delivery gives the debtor notice and opportunity to respond.
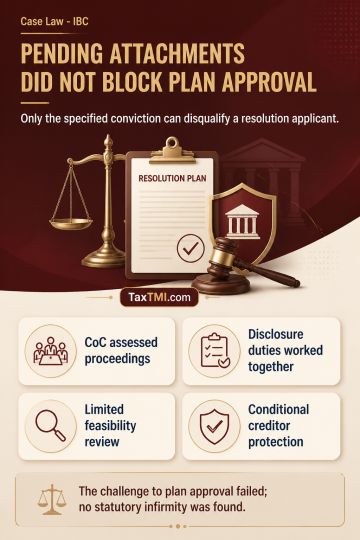
    PMLA proceedings and resolution applicant eligibility: pending attachments do not bar plan approval without the prescribed conviction.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Bulk drugs and active pharmaceutical ingredients qualify as "All...

Specific description-based IGST classification gives qualifying bulk drugs and APIs the concessional drugs-and-medicines rate over chemical entries.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Customs September 23, 2026 Case Laws AAR
Bulk drugs and active pharmaceutical ingredients qualify as "All Drugs and medicines" for concessional IGST treatment where they meet the drug description and are not within the prescribed nil-rate exclusion. The statutory drug definition includes substances intended for use as drug components; importing APIs for testing, clinical research, clinical trials, bioavailability, or bioequivalence studies does not alone change that status. The drugs-and-medicines entry applies across tariff chapters and prevails over general Chapter 28 or 29 chemical entries under the specific-over-general classification principle. Qualifying APIs attract IGST at 5%, subject to examination of the exclusion for each imported product.

Topics

Acts Income Tax