Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adju...
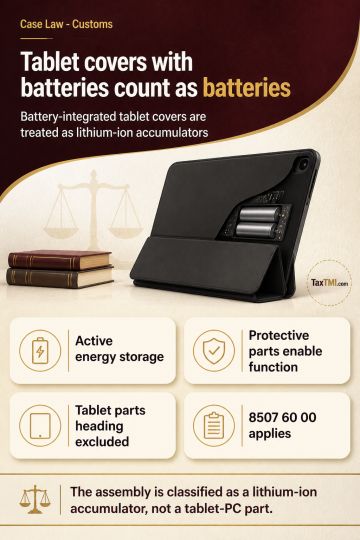
Battery-integrated tablet rear covers classify as lithium-ion accumulators when protective components enable the battery's active energy-storage funct...
Anti-profiteering computation for construction services must account for GST input tax credit that remained unutilised and was subsequently reversed. The additional credit benefit attributable to eligible homebuyers requires a commensurate reduction in price and must be passed on, including applicable GST, with 18% interest from collection of the excess amount until repayment. Penalty for failure to pass on the benefit does not apply to the relevant period because the penalty provision came into force only after that period ended.
Anti-profiteering computation for construction services must account for GST input tax credit that remained unutilised and was subsequently reversed. The additional credit benefit attributable to eligible homebuyers requires a commensurate reduction in price and must be passed on, including applicable GST, with 18% interest from collection of the excess amount until repayment. Penalty for failure to pass on the benefit does not apply to the relevant period because the penalty provision came into force only after that period ended.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881