Transfer-pricing aggregation of distinct support-service and subcontract transactions was rejected, while debt-free receivables attracted no notional ...
Customs exemptions cover photovoltaic assembly machinery and PVF backsheets, while fully declared cleared imports may avoid confiscation and penalties...
Specific tariff classification for LCD devices overrides treatment as electricity-meter parts, defeating differential duty, extended limitation, and p...
Stayed disciplinary punishment does not establish unfitness for insolvency professional registration; reconsideration must disregard mere pendency of ...
Indirect corporate control can create related-party status, excluding financial creditors from Committee of Creditors representation, participation an...
Scientific research association approval requires continuing SIRO status, annual donation reporting, and donor certificates for the approved foundatio...
Page of 4935
Press 'Enter' after typing page number.
1181 to 1200 of 98695 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Credit notes for returned or rejected processed-fabric supplies...
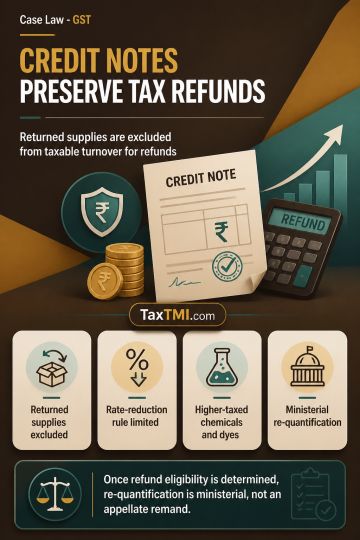
Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate remand.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Credit notes for returned or rejected processed-fabric supplies are excluded from outward taxable supply turnover when calculating an inverted-duty refund of accumulated input tax credit. The identical input-output supplies clarification is confined to accumulation caused by a rate reduction on the same goods over time; it does not apply where higher-taxed chemicals and dyes are used to process fabrics taxed at a lower rate without an output-rate reduction. Once refund eligibility and computational parameters are determined, consequential re-quantification is ministerial, does not reopen the merits, and does not constitute an appellate remand.
Credit notes for returned or rejected processed-fabric supplies are excluded from outward taxable supply turnover when calculating an inverted-duty refund of accumulated input tax credit. The identical input-output supplies clarification is confined to accumulation caused by a rate reduction on the same goods over time; it does not apply where higher-taxed chemicals and dyes are used to process fabrics taxed at a lower rate without an output-rate reduction. Once refund eligibility and computational parameters are determined, consequential re-quantification is ministerial, does not reopen the merits, and does not constitute an appellate remand.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935