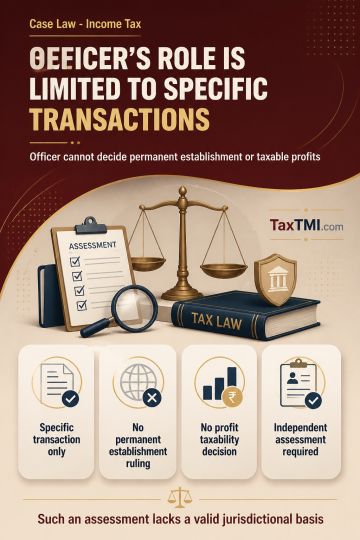
Transfer Pricing Officer jurisdiction is transaction-specific, excluding permanent establishment determinations and requiring independent assessment o...
Rental income valuation requires credible local comparables; family-business salary and commercially expedient unsecured-loan interest remained deduct...
Genuineness of agricultural receipts requires evidence of actual cultivation, including land details, crops and plantations, irrigation facilities, labour, horticultural borrowings and supporting photographs. Where such material establishes extensive agricultural operations, the reasonableness of net agricultural income must be assessed after accounting for disclosed cultivation expenditure and the scale of activity. Treating full gross agricultural receipts as income without allowing cultivation costs disregards the distinction between gross receipts and net income. Absence of cash deposits or unexplained investments may further support the stated agricultural source.
Genuineness of agricultural receipts requires evidence of actual cultivation, including land details, crops and plantations, irrigation facilities, labour, horticultural borrowings and supporting photographs. Where such material establishes extensive agricultural operations, the reasonableness of net agricultural income must be assessed after accounting for disclosed cultivation expenditure and the scale of activity. Treating full gross agricultural receipts as income without allowing cultivation costs disregards the distinction between gross receipts and net income. Absence of cash deposits or unexplained investments may further support the stated agricultural source.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881