Separate speaking orders on reopening objections are mandatory; deciding them within reassessment invalidates jurisdiction and precludes revival of st...
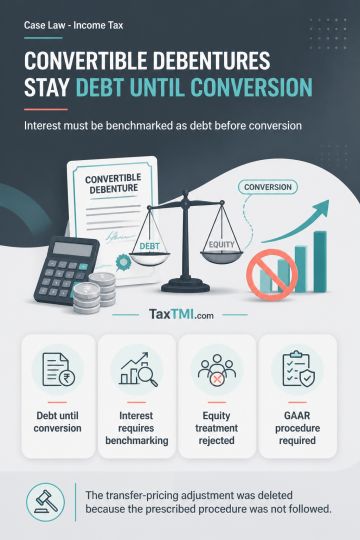
Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
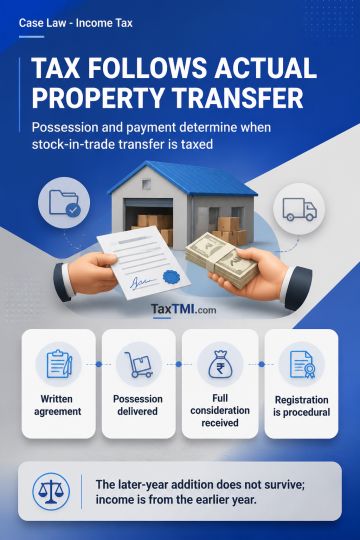
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
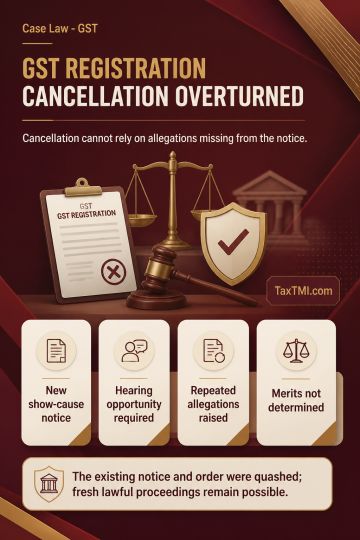
GST registration cancellation based on alleged fraudulent availment and passing of ineligible input tax credit cannot rest on grounds omitted from the show-cause notice. Repeated cancellation proceedings founded on allegations previously dropped by the same officer indicate non-application of mind. The cancellation notice and order were quashed without determination on the merits. Fresh proceedings may be initiated only through a new show-cause notice, with an opportunity of hearing and compliance with law.
GST registration cancellation based on alleged fraudulent availment and passing of ineligible input tax credit cannot rest on grounds omitted from the show-cause notice. Repeated cancellation proceedings founded on allegations previously dropped by the same officer indicate non-application of mind. The cancellation notice and order were quashed without determination on the merits. Fresh proceedings may be initiated only through a new show-cause notice, with an opportunity of hearing and compliance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4947



 Get Daily Updates