Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Page of 4942
Press 'Enter' after typing page number.
1221 to 1240 of 98829 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
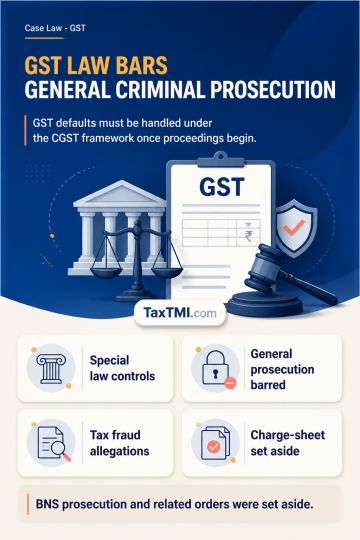
GST-related tax fraud allegations based on non-response and non-payment of Central or State GST must be addressed under the CGST Act where proceedings under that special enactment have already commenced. Sections 4 and 5 of the BNSS preserve the investigative and procedural framework prescribed by special statutes, preventing recourse to general criminal law for offences governed by such statutes. On this basis, BNS prosecution for the alleged GST defaults, including the charge-sheet and cognizance order against the taxpayer, was set aside.
GST-related tax fraud allegations based on non-response and non-payment of Central or State GST must be addressed under the CGST Act where proceedings under that special enactment have already commenced. Sections 4 and 5 of the BNSS preserve the investigative and procedural framework prescribed by special statutes, preventing recourse to general criminal law for offences governed by such statutes. On this basis, BNS prosecution for the alleged GST defaults, including the charge-sheet and cognizance order against the taxpayer, was set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4942