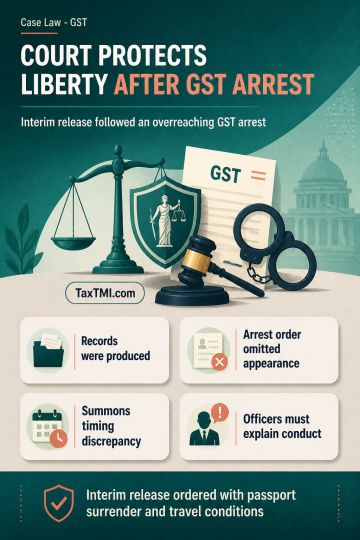
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
Page of 4934
Press 'Enter' after typing page number.
1281 to 1300 of 98666 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Input tax credit on land-survey charges incurred to identify alternate land for afforestation obligations is unavailable where the land is surrendered to the Forest Department, written off, and generates no independent economic benefit or taxable outward supply. The survey services are not used in the course or furtherance of business, so the Section 16(1) requirement is not met. Surveys connected with golf-course development concern immovable property developed on own account, while surveys for surrendered land relate to written-off land; the related credit is treated as blocked under Section 17(5), including Section 17(5)(h). Land transactions are outside the scope of supply under Schedule III.
Input tax credit on land-survey charges incurred to identify alternate land for afforestation obligations is unavailable where the land is surrendered to the Forest Department, written off, and generates no independent economic benefit or taxable outward supply. The survey services are not used in the course or furtherance of business, so the Section 16(1) requirement is not met. Surveys connected with golf-course development concern immovable property developed on own account, while surveys for surrendered land relate to written-off land; the related credit is treated as blocked under Section 17(5), including Section 17(5)(h). Land transactions are outside the scope of supply under Schedule III.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4934