Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
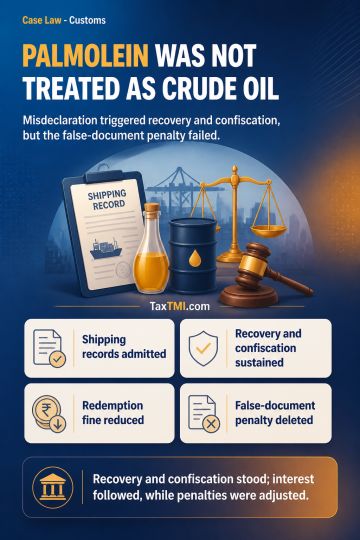
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
Service of reassessment notices under section 148A(b) must provide the petitioner a genuine opportunity to respond. Where notices and the section 148A(d) order were sent to a secondary email address and a former residential address, a further response opportunity was warranted. The reassessment notice and order, assessment, consequential demands, penalty orders and recovery notice were quashed, while reassessment proceedings were restored and the petitioner was permitted to respond within the stipulated time. Merits remained open.
Service of reassessment notices under section 148A(b) must provide the petitioner a genuine opportunity to respond. Where notices and the section 148A(d) order were sent to a secondary email address and a former residential address, a further response opportunity was warranted. The reassessment notice and order, assessment, consequential demands, penalty orders and recovery notice were quashed, while reassessment proceedings were restored and the petitioner was permitted to respond within the stipulated time. Merits remained open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4939