Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
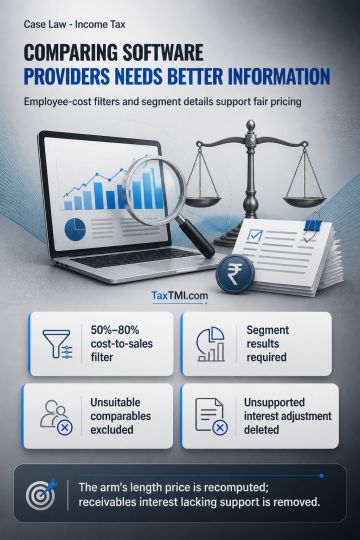
Transfer-pricing benchmarking of software development services applies an employee-cost-to-sales filter within 50% to 80%, requiring recomputation of the arm's length price on that basis. Comparables without segmental results, entities affected by an extraordinary amalgamation, and businesses performing materially different functions are excluded. Overdue associated-enterprise receivables are international transactions, but an interest adjustment under the CUP method requires identified segmental comparables, supporting material, and computation consistent with segmental trends; an unsupported adjustment is deleted. Working-capital differences require fresh examination under applicable transfer-pricing principles.
Transfer-pricing benchmarking of software development services applies an employee-cost-to-sales filter within 50% to 80%, requiring recomputation of the arm's length price on that basis. Comparables without segmental results, entities affected by an extraordinary amalgamation, and businesses performing materially different functions are excluded. Overdue associated-enterprise receivables are international transactions, but an interest adjustment under the CUP method requires identified segmental comparables, supporting material, and computation consistent with segmental trends; an unsupported adjustment is deleted. Working-capital differences require fresh examination under applicable transfer-pricing principles.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4879