Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
Modified returns after business reorganisation must be assessed within pending proceedings, barring parallel scrutiny and consequential transfer prici...
Turnover mismatches under percentage-completion accounting cannot alone establish suppressed income where customer advances remain recorded as liabili...
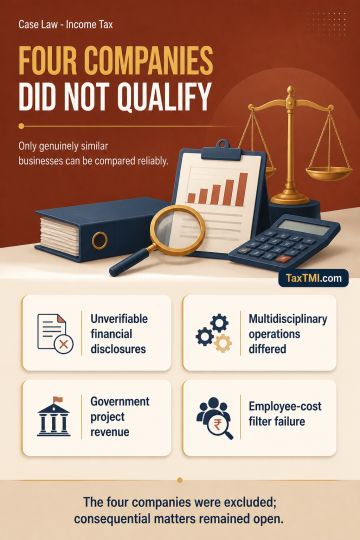
Transfer-pricing benchmarking of software development services applies an employee-cost-to-sales filter within 50% to 80%, requiring recomputation of the arm's length price on that basis. Comparables without segmental results, entities affected by an extraordinary amalgamation, and businesses performing materially different functions are excluded. Overdue associated-enterprise receivables are international transactions, but an interest adjustment under the CUP method requires identified segmental comparables, supporting material, and computation consistent with segmental trends; an unsupported adjustment is deleted. Working-capital differences require fresh examination under applicable transfer-pricing principles.
Transfer-pricing benchmarking of software development services applies an employee-cost-to-sales filter within 50% to 80%, requiring recomputation of the arm's length price on that basis. Comparables without segmental results, entities affected by an extraordinary amalgamation, and businesses performing materially different functions are excluded. Overdue associated-enterprise receivables are international transactions, but an interest adjustment under the CUP method requires identified segmental comparables, supporting material, and computation consistent with segmental trends; an unsupported adjustment is deleted. Working-capital differences require fresh examination under applicable transfer-pricing principles.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI