Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
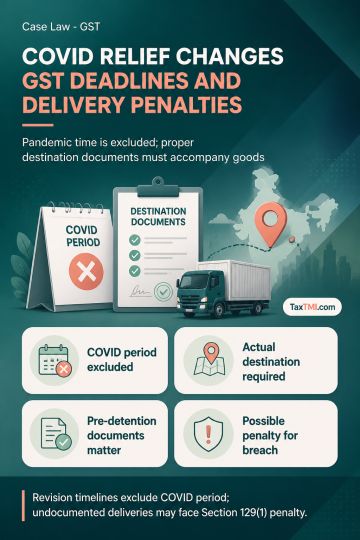
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Questions arising from miscellaneous application orders cannot challenge unaltered Tribunal findings, leaving the original order separately challengea...
Transfer-pricing comparability filters require fresh arm's-length analysis, while delayed receivables need separate reconsideration with working-capit...
Section 92CD(3) requires an assessment for a year covered by a unilateral advance pricing agreement to be completed in accordance with that agreement when proceedings remain pending and a modified return is filed. For AY 2022-23, compliance with the UAPA and filing of the modified return meant that retaining the original transfer-pricing adjustment without considering the modified return was erroneous. The assessment must be completed after taking the modified return into account and applying the UAPA terms and conditions.
Section 92CD(3) requires an assessment for a year covered by a unilateral advance pricing agreement to be completed in accordance with that agreement when proceedings remain pending and a modified return is filed. For AY 2022-23, compliance with the UAPA and filing of the modified return meant that retaining the original transfer-pricing adjustment without considering the modified return was erroneous. The assessment must be completed after taking the modified return into account and applying the UAPA terms and conditions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4934