Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
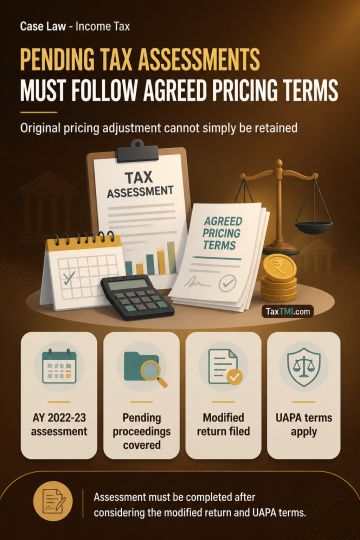
Section 92CD(3) requires an assessment for a year covered by a unilateral advance pricing agreement to be completed in accordance with that agreement when proceedings remain pending and a modified return is filed. For AY 2022-23, compliance with the UAPA and filing of the modified return meant that retaining the original transfer-pricing adjustment without considering the modified return was erroneous. The assessment must be completed after taking the modified return into account and applying the UAPA terms and conditions.
Section 92CD(3) requires an assessment for a year covered by a unilateral advance pricing agreement to be completed in accordance with that agreement when proceedings remain pending and a modified return is filed. For AY 2022-23, compliance with the UAPA and filing of the modified return meant that retaining the original transfer-pricing adjustment without considering the modified return was erroneous. The assessment must be completed after taking the modified return into account and applying the UAPA terms and conditions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881