Modified returns after business reorganisation must be assessed within pending proceedings, barring parallel scrutiny and consequential transfer prici...
Turnover mismatches under percentage-completion accounting cannot alone establish suppressed income where customer advances remain recorded as liabili...
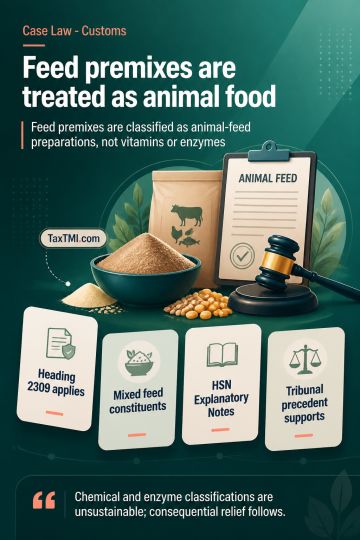
Vitamin and enzyme premixes used as animal-feed additives are classifiable as preparations of a kind used in animal feeding under Customs Tariff Heading 2309, rather than as vitamins or pro-vitamins under heading 2936 or enzymes under heading 3507. Classification requires a comprehensive comparison of competing tariff entries and applicable HSN Explanatory Notes. Premixes containing vitamins, minerals, trace elements, appetisers, soya flour or meal, yeast and comparable constituents support classification within animal-feed preparations. Tribunal and Supreme Court precedent, together with a later Tribunal ruling on animal-feed additives, support this tariff treatment. Classification under the chemical and enzyme headings is unsustainable, with consequential relief following.
Vitamin and enzyme premixes used as animal-feed additives are classifiable as preparations of a kind used in animal feeding under Customs Tariff Heading 2309, rather than as vitamins or pro-vitamins under heading 2936 or enzymes under heading 3507. Classification requires a comprehensive comparison of competing tariff entries and applicable HSN Explanatory Notes. Premixes containing vitamins, minerals, trace elements, appetisers, soya flour or meal, yeast and comparable constituents support classification within animal-feed preparations. Tribunal and Supreme Court precedent, together with a later Tribunal ruling on animal-feed additives, support this tariff treatment. Classification under the chemical and enzyme headings is unsustainable, with consequential relief following.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4879