Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
Strict construction of customs exemptions denied concession for brake components, while limitation restricted differential duty to timely Bills of Ent...
Inter-terminal container movement requires customs escort, permit reconciliation, and indemnity, while delayed DPD cargo may move to designated CFS ya...
Page of 593
Press 'Enter' after typing page number.
1 to 20 of 11857 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
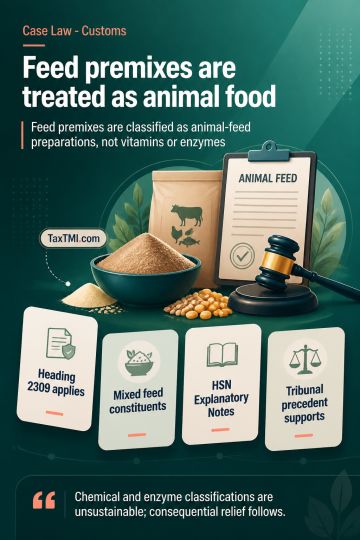
Vitamin and enzyme premixes used as animal-feed additives are classifiable as preparations of a kind used in animal feeding under Customs Tariff Heading 2309, rather than as vitamins or pro-vitamins under heading 2936 or enzymes under heading 3507. Classification requires a comprehensive comparison of competing tariff entries and applicable HSN Explanatory Notes. Premixes containing vitamins, minerals, trace elements, appetisers, soya flour or meal, yeast and comparable constituents support classification within animal-feed preparations. Tribunal and Supreme Court precedent, together with a later Tribunal ruling on animal-feed additives, support this tariff treatment. Classification under the chemical and enzyme headings is unsustainable, with consequential relief following.
Vitamin and enzyme premixes used as animal-feed additives are classifiable as preparations of a kind used in animal feeding under Customs Tariff Heading 2309, rather than as vitamins or pro-vitamins under heading 2936 or enzymes under heading 3507. Classification requires a comprehensive comparison of competing tariff entries and applicable HSN Explanatory Notes. Premixes containing vitamins, minerals, trace elements, appetisers, soya flour or meal, yeast and comparable constituents support classification within animal-feed preparations. Tribunal and Supreme Court precedent, together with a later Tribunal ruling on animal-feed additives, support this tariff treatment. Classification under the chemical and enzyme headings is unsustainable, with consequential relief following.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI