Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
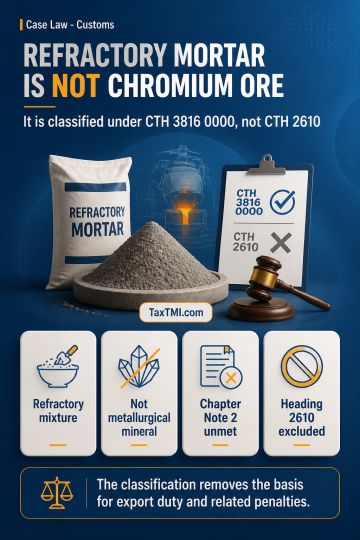
Indian Refractory Mortar, being a mixture used as refractory mortar rather than a mineral employed in metallurgical extraction of chromium, does not meet Chapter Note 2 to Chapter 26. It is therefore classifiable under CTH 3816 0000, not CTH 2610 for chromium ores and concentrates. This classification removes the basis for export duty and consequential penalties.
Indian Refractory Mortar, being a mixture used as refractory mortar rather than a mineral employed in metallurgical extraction of chromium, does not meet Chapter Note 2 to Chapter 26. It is therefore classifiable under CTH 3816 0000, not CTH 2610 for chromium ores and concentrates. This classification removes the basis for export duty and consequential penalties.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881