Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
Non-participating bidders cannot disturb concluded liquidation sales on speculative prejudice, while costs for such challenges must remain proportiona...
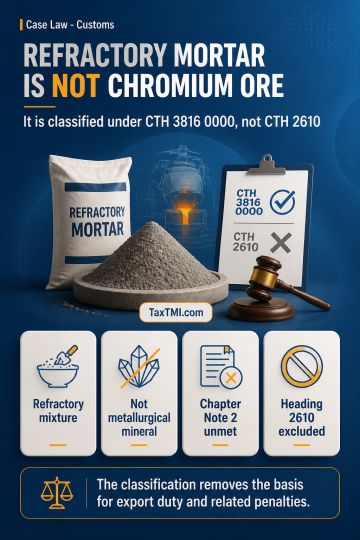
Indian Refractory Mortar, being a mixture used as refractory mortar rather than a mineral employed in metallurgical extraction of chromium, does not meet Chapter Note 2 to Chapter 26. It is therefore classifiable under CTH 3816 0000, not CTH 2610 for chromium ores and concentrates. This classification removes the basis for export duty and consequential penalties.
Indian Refractory Mortar, being a mixture used as refractory mortar rather than a mineral employed in metallurgical extraction of chromium, does not meet Chapter Note 2 to Chapter 26. It is therefore classifiable under CTH 3816 0000, not CTH 2610 for chromium ores and concentrates. This classification removes the basis for export duty and consequential penalties.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881